BVI overhauls the annual financial return: new FSC form in force from 2 November 2026
The BVI FSC's new annual financial return form, in force from 2 Nov 2026, asks for banks, loans, portfolio and income by type. For returns filed from 2027.
The BVI FSC's new annual financial return form, in force from 2 Nov 2026, asks for banks, loans, portfolio and income by type. For returns filed from 2027.
 ▸ Regulatory
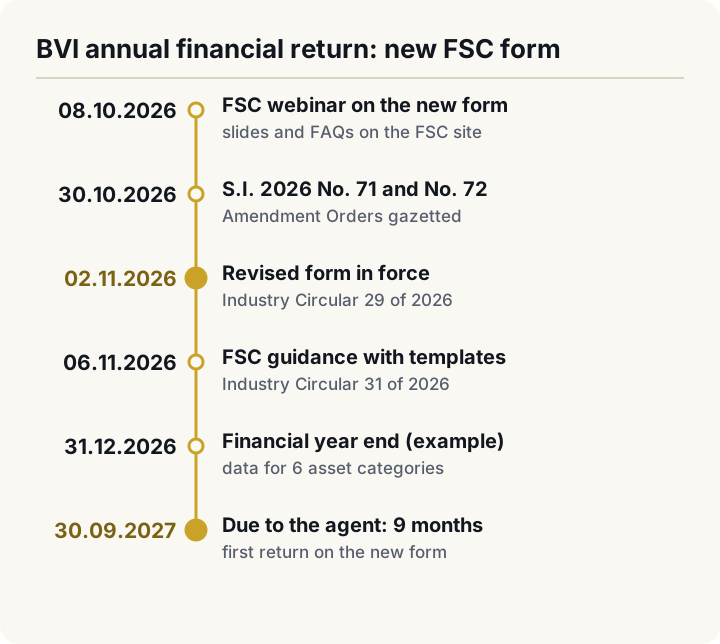
The BVI Financial Services Commission (BVI FSC) brought a new annual financial return form for BVI companies and limited partnerships into force on 2 November 2026. The BVI Business Companies (Financial Return) (Amendment) Order, 2026 (S.I. 2026 No. 71) replaces the form schedule of the 2023 Order and asks for more detail on assets, revenue and expenses. The new form applies to returns filed from 2027 onwards. For a holding company or family office with a 31 December 2026 year end, this is the first return under the new rules: it goes to the registered agent within 9 months, by 30 September 2027. On 6 November the FSC published completion guidance with worked templates (Industry Circular 31 of 2026).
Running a BVI holding company or family office? An INNOVA partner reviews the company's asset structure, collects the bank, loan and investment data the new form asks for, and aligns the return with your registered agent. Send an enquiry →
The annual financial return obligation sits in section 98A of the BVI Business Companies Act, Revised Edition 2020, and in section 54A of the Limited Partnership Act for limited partnerships. The return is filed with the company's registered agent. The FSC sets the form by order.
| Date | Event | Instrument |
|---|---|---|
| 08.10.2026 | FSC webinar on the upcoming changes (slides and FAQs available on the FSC site) | Industry Circular 29 of 2026 |
| 30.10.2026 | Amendment Orders gazetted | S.I. 2026 No. 71 (companies), S.I. 2026 No. 72 (LPs) |
| 02.11.2026 | Amendment Orders in force; FSC circular issued | Industry Circular 29 of 2026 |
| 06.11.2026 | Guidance on completing the revised form, with templates | Industry Circular 31 of 2026 |
| From 2027 | Every annual return is filed on the revised form | Industry Circular 29 of 2026; FSC Guidance, para 1.2 |
In the FSC's words, the changes cover the form of filing and the information required: companies report additional information on assets, revenue and expenses, and limited partnerships on assets, income and expenses.
The revised form has a balance sheet (assets, liabilities, equity) and an income statement. Total assets must equal liabilities plus shareholders' equity. Assets fall into six categories, each with a list and a valuation.
In the income statement, revenue is categorised by type: for a holding company that means dividend income, interest income and gains. A holding company usually has no cost of sales and enters N/A. Expenses split into operating expenses (by type), other expenses and income tax expense, which includes foreign income taxes and withholding taxes.
For a BVI family office structure, the 2026 return will show the agent every bank with its jurisdiction, the portfolio split by asset type, and intra-family or intra-group loans where they exceed a quarter of the balance sheet. Collect this data before the year closes, while statements and 31 December valuations are easy to obtain.
Before 31 December 2026:
Agree the timeline and valuation approach with the agent early. Preparing data for a complex portfolio usually takes several weeks.
Returns filed from 2027 onwards. S.I. 2026 No. 71 has been in force since 2 November 2026, and the FSC's Circular 29 and its guidance apply the revised form to every annual return filed from 2027.
With the company's registered agent, within 9 months after the financial year end. The requirement is in section 98A of the BVI Business Companies Act and, for limited partnerships, section 54A of the Limited Partnership Act.
A detailed split is needed where loans and receivables are 25% or more of total assets: amounts for related party loans, third party loans and other, with the number of loans. Below the threshold, the total and a note that the threshold is not met are enough.
INNOVA supports BVI companies together with the registered agent, the bank and the bookkeeping through one partner. A partner replies within 24 hours, and the price is fixed once the scope is clear.
Send an enquiry → · BVI family office · Book the $99 strategy session, credited to the project
Sources: BVI FSC, Industry Circular 29 of 2026 (02.11.2026); BVI Business Companies (Financial Return) (Amendment) Order, 2026, S.I. 2026 No. 71; Limited Partnership (Financial Return) (Amendment) Order, 2026, S.I. 2026 No. 72; BVI FSC, Industry Circular 31 of 2026 (06.11.2026); Guidance on Completing Annual Financial Returns (06.11.2026).
Information only, primary sources as of 07.11.2026. Filing practice and asset valuation are confirmed with the company's registered agent.
This material is for general information only and does not constitute legal or tax advice. Accurate as of the publication date.